
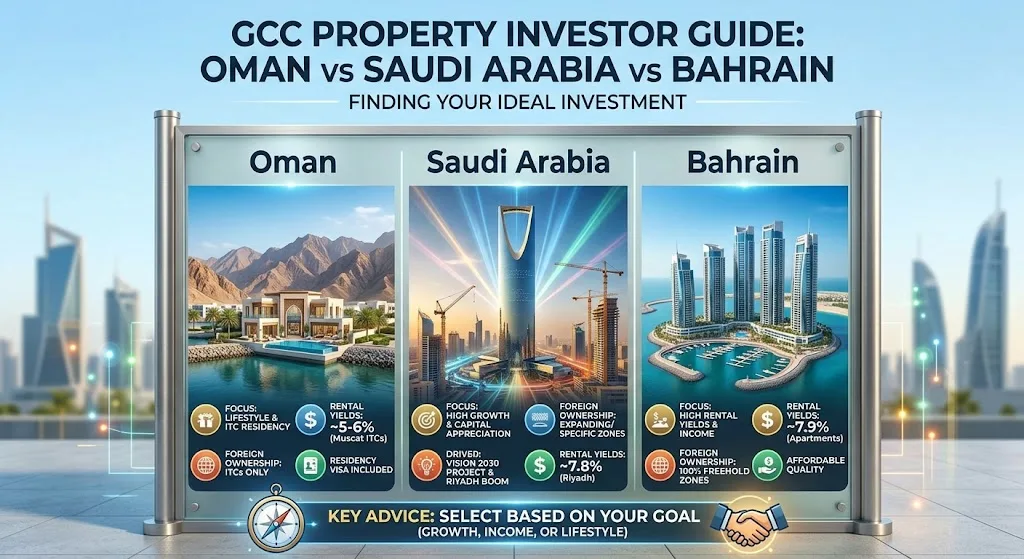
Regional investors comparing GCC property markets usually default to Dubai, and understandably — it's the deepest and best-documented. But Saudi Arabia, Bahrain and Oman are each doing something distinct right now, and lumping them together as "the rest of the Gulf" misses real differences in access, cost, and market stage. Here's the honest comparison, with the caveat upfront: we track Oman's market in depth on this site; Saudi and Bahrain figures below come from general published market reporting rather than our own tracked area dataset, so treat them as directional context, not the granular figures we'd give you for Oman.
The structural picture#
| Oman | Saudi Arabia | Bahrain | |
|---|---|---|---|
| Foreign ownership | Licensed ITC zones only (Royal Decree 12/2006) | Historically restricted; opening in designated zones from 2026 under Vision 2030 | Designated investment areas, GCC and non-GCC nationals |
| Market maturity | Small, early-stage freehold market | Very large market; foreign-ownership segment newly opening | Longest-established foreign freehold framework of the three |
| Entry pricing (indicative) | Lowest of the three — Muscat ITC from ~OMR 60-140/sqft equivalent | Highest overall, driven by Riyadh's scale and giga-project pricing | Mid-range, generally below Riyadh prime |
| Annual property tax | None | None on residential ownership, but 5% RETT on transfer | None on residential ownership |
| Residency-by-investment | From OMR 250,000 (5-year), OMR 500,000 (10-year) | Premium Residency scheme, separate from property purchase specifically | Golden residency available via qualifying investment, including real estate |
Oman figures per our own tracked dataset and methodology; Saudi Arabia and Bahrain figures are general market context from published sources, not our own tracked data.
Oman: the lowest entry price, the smallest market#
Oman's case is straightforward: the lowest absolute entry prices of the three, no annual property tax, and a genuinely improving regulatory picture — the 2026 Real Estate Registry Law and sponsor-free owner's residence permit both moved in foreign buyers' favour, as we covered in what actually changed in 2026. The trade-off is scale: foreign ownership is restricted to a short list of licensed ITC communities, resale liquidity is thin, and public transaction data is limited compared to more mature markets. Our full Oman vs Dubai comparison covers the liquidity and data gap in more depth against a market most investors already understand.
Saudi Arabia: the largest market, but foreign access is new#
Saudi Arabia's real estate market dwarfs Oman's and Bahrain's on any measure — driven by Vision 2030 giga-projects (NEOM, Qiddiya, the Red Sea developments) and a domestic market with far greater depth. What's changed recently is access: the kingdom has been moving toward opening foreign ownership in designated zones, a genuinely significant shift given how restricted it was historically outside the holy cities. The important caveat for anyone reading this as an investment thesis: rules here are new and actively evolving. Treat any specific claim about foreign-ownership eligibility as something to verify directly and currently, not something to take from any single article, including this one.
Saudi Arabia also applies a 5% Real Estate Transaction Tax (RETT) on property transfers, which is a materially different cost structure from Oman's ~3% registration fee — worth factoring in before assuming Saudi pricing is directly comparable to Oman's on a like-for-like basis.
Bahrain: the most established foreign-ownership framework#
Of the three, Bahrain has had open foreign freehold ownership in designated investment areas the longest, which shows up in a comparatively deeper and more liquid foreign-buyer market than either Oman or Saudi Arabia currently offer. It doesn't carry Saudi Arabia's giga-project growth narrative or Oman's rock-bottom entry pricing, but for an investor prioritising a track record of foreign ownership actually working smoothly over time, Bahrain's longer history is itself a data point worth weighing.
What this doesn't mean#
The instinct to rank these three markets on a single "best" axis is the wrong frame — the same mistake as ranking Oman against Dubai on price alone. Each is offering a different trade:
- Oman: lowest price, smallest and least liquid market, clearest no-tax structure.
- Saudi Arabia: largest growth story, newest and least-tested foreign-access rules.
- Bahrain: most established foreign-ownership track record, less headline growth narrative than Saudi.
None of these is a forecast that any market will outperform the others — it's a description of what each is actually offering right now, and the risk profile that comes attached to it.
Putting the same OMR 100,000 to work in each market#
Oman: at Muscat Bay's OMR 100/sqft, OMR 100,000 buys roughly 100 sqm — a solid two-bedroom — with a tracked 7.0% gross yield, no annual property tax, and a ~5% all-in buyer cost. Bahrain: the same budget, at established investment-area pricing, typically buys a smaller or older unit given Bahrain's more mature, higher-priced foreign-ownership market, but with a longer track record of foreign buyers actually transacting and exiting smoothly. Saudi Arabia: OMR 100,000 (roughly SAR 970,000) is a modest budget against Riyadh's newly-opening foreign-ownership zones, where entry pricing skews toward the giga-project narrative rather than value entry points, and — critically — where the buyer would still need to confirm current eligibility for that specific zone before assuming the purchase is even permitted. The same capital buys a materially different asset, and a materially different risk profile, in each market.
What to actually check before choosing#
- Verify current foreign-ownership eligibility directly, especially for Saudi Arabia, where rules are moving fastest.
- Compare total transaction cost, not just headline price — Saudi's 5% RETT, Oman's ~5-8% all-in buyer cost, and Bahrain's own fee structure aren't directly comparable without doing that conversion.
- Weigh liquidity against price. Oman's lower prices come with a smaller resale pool; that trade-off matters more the shorter your likely holding period.
- Decide what you're actually underwriting — Saudi Arabia's growth story, Bahrain's track record, or Oman's entry price and tax structure are different bets, not variations on the same one.
For the market we track in depth, our area comparison tool and Oman market report give the granular figures Saudi and Bahrain coverage here deliberately doesn't claim to match.
Sources: Oman figures from our own tracked area dataset, per our methodology; Saudi Arabia and Bahrain figures from general published GCC real estate market reporting and each country's foreign-ownership policy announcements as of 2026 — verify current rules directly given how quickly Saudi Arabia's framework in particular is evolving.